AlphaVeyra — Financial Quant Insights
AlphaVeyra — Financial Quant Insights
Turn a quantitative research hypothesis into traceable evidence: checked inputs, declared assumptions, chronological experiments, charged costs and an independent audit of recorded results. AlphaVeyra is a downloadable Agent Skill for local financial research and offline strategy validation.
Actual output from the included demonstration
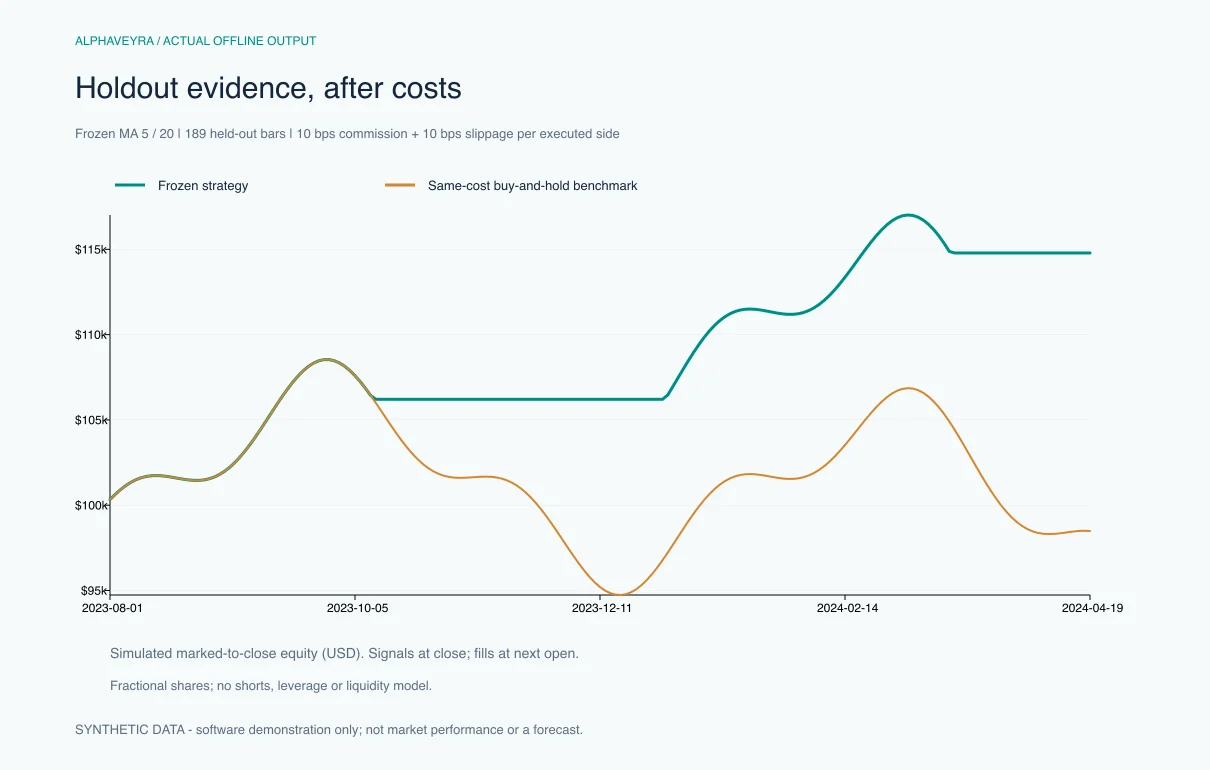
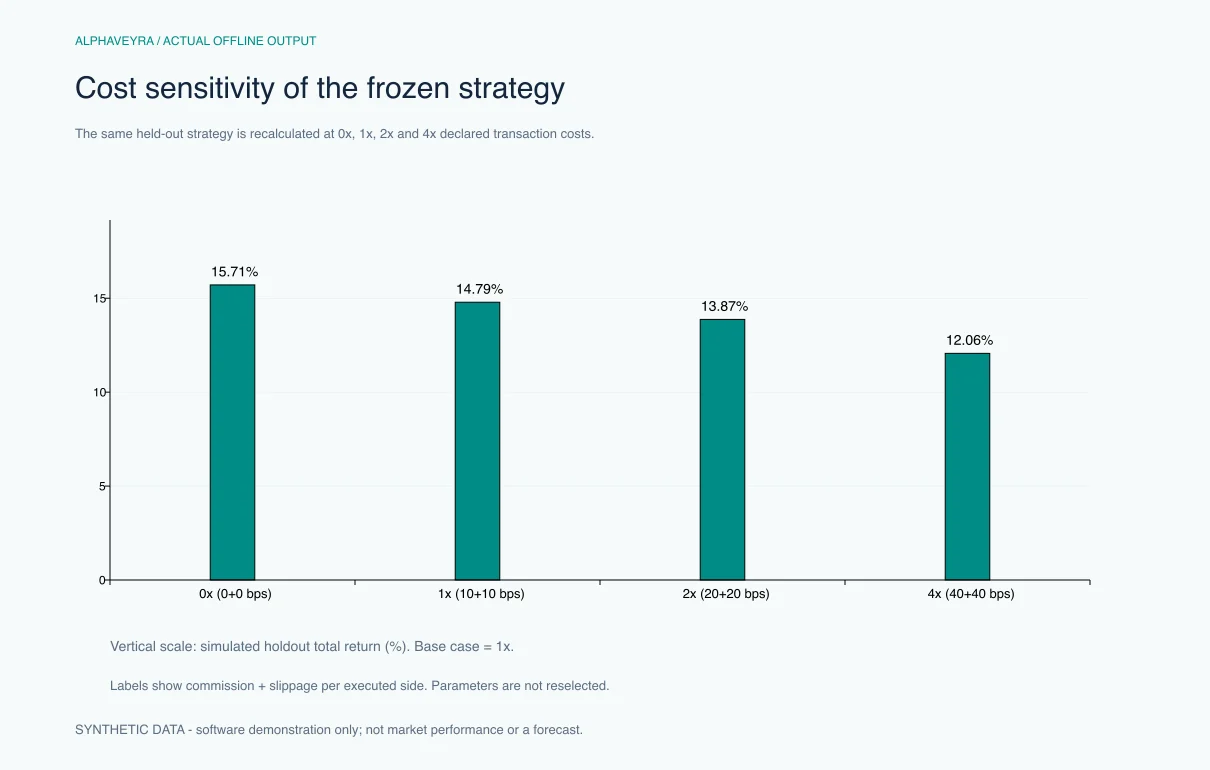
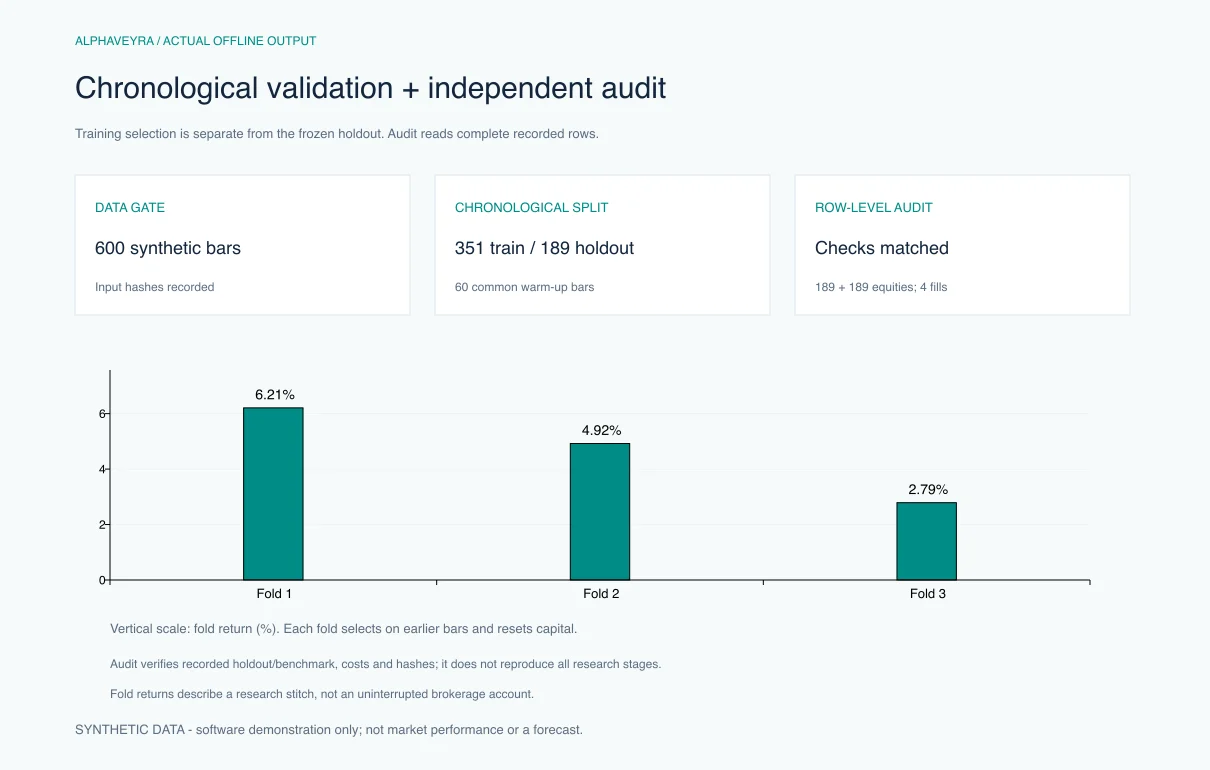
The figures below were plotted from a real execution of the included v2.0.4 scripts using 600 synthetic daily bars. They show the frozen holdout, transaction-cost sensitivity, expanding validation and recorded-result audit. They are supplementary visualizations of the generated CSV/JSON artifacts. The inputs are synthetic: these figures demonstrate the software, not real-market returns, investment recommendations or expected performance. The original inputs, HTML/JSON report, complete CSV records, file manifest and audit are included in the download.
Holdout evidence after costs
Transaction-cost sensitivity
Chronological validation and recorded-result audit
What the Skill helps you do
- Validate local data: inspect daily CSVs for duplicate or out-of-order dates, missing columns, invalid prices, inconsistent OHLC bounds and volume issues; preserve input fingerprints.
- Run declared experiments: compare predeclared moving-average candidates, select using training history and freeze the selected parameters for a separate chronological holdout.
- Account for costs: model commission and slippage per executed side, compare with a same-cost buy-and-hold benchmark and stress the frozen strategy at different cost levels.
- Inspect robustness: produce expanding-window folds, built-in signal prefix checks and a seeded block-bootstrap summary conditional on the observed held-out returns.
- Audit recorded evidence: independently recalculate the complete holdout/benchmark equity records, fills, transaction costs and file integrity. This audit does not reproduce candidate selection, stress runs, expanding folds or bootstrap calculations.
- Read and share results: generate a self-contained HTML report, JSON evidence, CSV records and a SHA256 artifact manifest. Optional helpers support reviewed local Vibe-Trading calculations when a separate runtime is installed.
What you receive
One downloadable package containing:
SKILL.mdand Agent metadata for AlphaVeyra v2.0.4.- Six Python helper scripts and four focused workflow references.
- An English/Chinese buyer guide and runtime requirements notes.
- A complete synthetic demonstration with original inputs, full recorded outputs, independent audit and all three figures shown above.
- MIT license and third-party provenance notices.
Capafy's first listing version is v1.0.0; the included Skill code is v2.0.4. Price: US$12.90, one-time download.
How to use it
- Extract the package and place the
alphaveyrafolder in the skills directory supported by your Agent client. The client needs local file access and Python execution. - Invoke
$alphaveyrawhere supported, or loadSKILL.mdas the workflow instructions. Start with the supplied synthetic demonstration before using your own dataset. - Provide your own daily OHLC CSV, symbol, quote currency, date range, candidate windows and explicit costs. Keep the initial experiment declaration intact after inspecting its holdout.
- Open the generated HTML report and run the independent recorded-result audit. Inspect assumptions and audit findings alongside the figures.
Example request: “Use AlphaVeyra to validate my supplied daily CSV, compare these predeclared moving-average windows with a chronological holdout, test commission/slippage sensitivity, and audit the recorded result without accessing any user account.”
Requirements and scope
The independent JSON/CSV core uses Python 3.9+ and its standard library; it requires no upstream application or API key. YAML mappings optionally require PyYAML. Optional local Vibe-Trading features need Python 3.11+, a separately installed upstream application and its dependencies. These are not bundled. Any Agent-client or service costs are separate from this download. Compatibility across all Agent clients and execution inside Capafy have not been established.
The standard lab supports a single instrument, long/flat moving-average signals, daily bars and fractional shares. It does not model shorts, leverage, venue lots, settlement, corporate actions, taxes, financing or liquidity. Data adjustment and redistribution rights cannot be verified from CSV alone. The bootstrap summary is conditional on observed returns, not a future-return guarantee or a selection-adjusted significance test. Input hashes establish recorded consistency, not authenticity or complete model validity.
Analysis and offline simulation only. This edition does not support accessing or operating real user accounts, account-authenticated provider workflows, live trading, order placement or credentialed upstream MCP services. Use public anonymous information or local files that the user independently exported and supplied. A successful run or clean audit does not establish future profitability.
Licensing and provenance
AlphaVeyra is an independently implemented edition with optional compatibility helpers for HKUDS/Vibe-Trading, not an official HKUDS/Vibe-Trading product. The included material is MIT-licensed; paid distribution preserves the permissions in LICENSE. Optional upstream software and dependencies retain their respective licenses. See THIRD_PARTY_NOTICES.md for the reviewed commit and distribution scope.
AlphaVeyra · 金融量化洞察
把量化研究假设变成可追溯证据:输入数据检查、明确的模型假设、按时间顺序划分的实验、计入成本的结果,以及对记录结果的独立复核。这是一款用于本地金融研究和离线策略验证的 Agent Skill 下载包。
详情中的实际结果图
上方三张图来自本次实际运行的 v2.0.4 脚本,以 600 条合成日线数据演示冻结参数后的留出结果、交易成本敏感性、扩展窗口验证和记录审计。这些图由实际生成的 CSV/JSON 记录绘制,是补充可视化。示例数据是合成数据,只用于展示软件功能,不是真实行情收益、投资建议或预期表现。 下载包保留原始输入、完整 HTML/JSON 报告、CSV 记录、文件清单、独立审计及全部三张图。
主要能力
- 检查本地日线 CSV 的日期重复或乱序、缺失列、无效价格、OHLC 不一致与成交量问题,并记录输入指纹。
- 比较预先声明的均线候选参数,使用训练期选择参数,再冻结到独立的时间留出期。
- 按每次成交单边计入手续费和滑点,与相同成本的买入持有基准比较,并进行成本压力测试。
- 生成扩展窗口验证、内置均线信号前缀检查,以及基于已观察留出收益的区块重采样摘要。
- 独立重算完整留出期与基准的资金记录、成交、成本和文件完整性。此审计不重新执行参数选择、成本压力、扩展窗口或重采样计算。
- 输出独立 HTML 报告、JSON 证据、CSV 记录和 SHA256 文件清单。安装额外环境后,可使用经说明的 Vibe-Trading 本地计算辅助功能。
下载交付
包含 AlphaVeyra v2.0.4 的 SKILL.md 与 Agent 元数据、六个 Python 辅助脚本、四份流程参考、完整中英买家指南、运行要求说明、合成演示及完整输出、三张图、MIT 许可与第三方来源声明。Capafy 首次上架版本为 v1.0.0,技能代码版本为 v2.0.4。
售价 US$12.90,一次性下载。
使用方法
- 解压后,将
alphaveyra放入 Agent 客户端支持的技能目录。客户端需要读取本地文件和运行 Python。 - 在支持的客户端中调用
$alphaveyra,或加载SKILL.md。建议先运行随包演示,再使用自己的数据。 - 提供日线 OHLC CSV、标的、币种、日期、预先声明的均线参数和明确成本。看过留出结果后,应保留原始实验声明。
- 阅读生成的 HTML 报告,运行独立记录审计,结合图表检查假设和审计发现。
示例请求:“使用 AlphaVeyra 检查我提供的日线 CSV,按时间划分训练与留出期比较这些预先声明的均线参数,分析手续费和滑点敏感性,并审计记录结果,不接入任何真实账户。”
运行要求与范围
独立 JSON/CSV 核心仅需 Python 3.9+ 标准库,无需上游应用或 API Key。YAML 映射可选使用 PyYAML。可选 Vibe-Trading 本地功能需要 Python 3.11+ 及另行安装的上游程序和依赖,下载包不捆绑这些环境。Agent 客户端或服务费用另计;没有验证所有客户端的兼容性或在 Capafy 内直接执行的能力。
标准研究核心仅支持单标的、均线多头/空仓、日线和碎股,未建模空头、杠杆、市场整手规则、结算、公司行动、税费、融资与流动性。CSV 不能证明复权适当或数据再分发权。区块重采样摘要仅取决于已观察收益,不能保证未来收益,也不是针对参数搜索校正后的显著性检验。文件指纹说明记录一致性,不证明真实性或完整模型有效性。
仅用于分析和离线模拟。 本版不支持登录、接入、读取或操作任何真实使用者账户,不支持实盘、下单、使用账户凭证的数据服务和上游 MCP 服务。可使用无需登录的公开信息,或使用者自行导出并提供的本地文件。运行或审计通过不能证明未来盈利。
许可与来源
本版核心独立实现,包含对 HKUDS/Vibe-Trading 的可选兼容辅助功能,不是 HKUDS/Vibe-Trading 官方商品。随包内容采用 MIT 许可,付费分发保留 LICENSE 已授予的权利。可选上游程序及依赖分别适用原许可;核对提交与交付范围见 THIRD_PARTY_NOTICES.md。