US Stock Picker & Algo Lab
US Stock Picker & Algo Lab
Stop guessing which stocks to hold. This agent ranks any US universe, finds strategies that survive out-of-sample testing, and deploys to IBKR paper trading — with institutional anti-overfit discipline and zero API keys required.
No CSV upload. No subscriptions. No broker credentials in the cloud. Free daily market data.
Watch it work
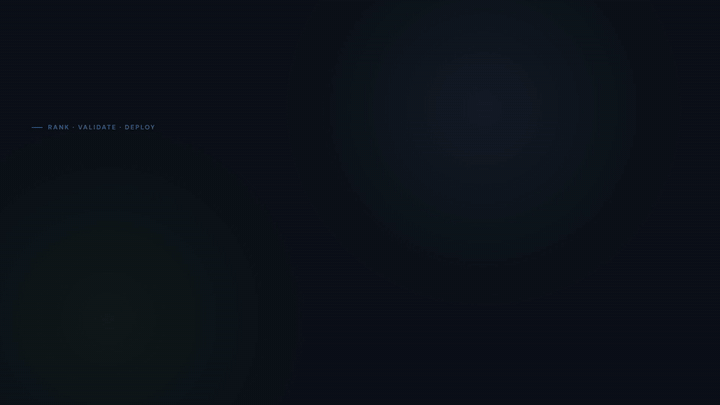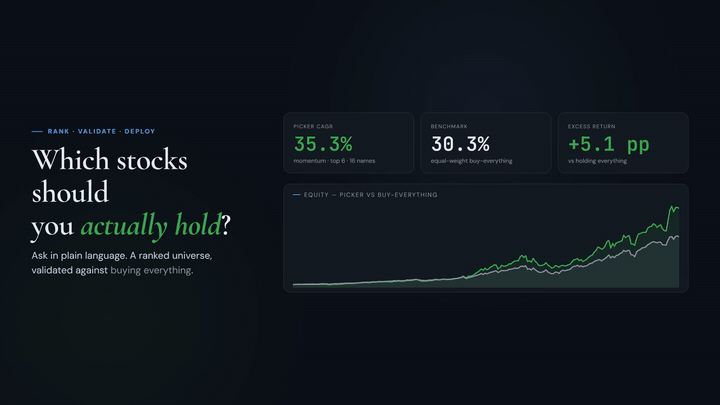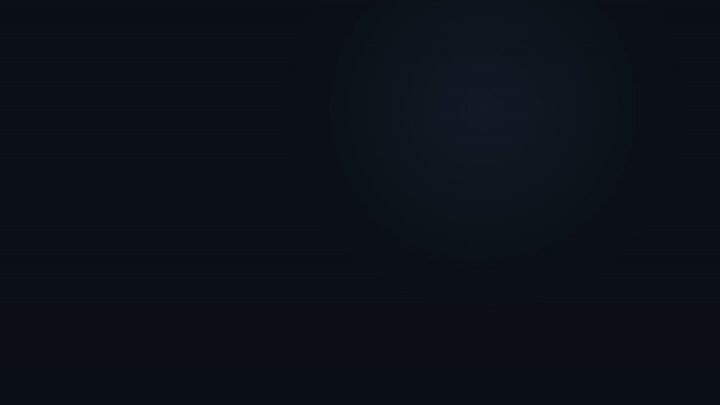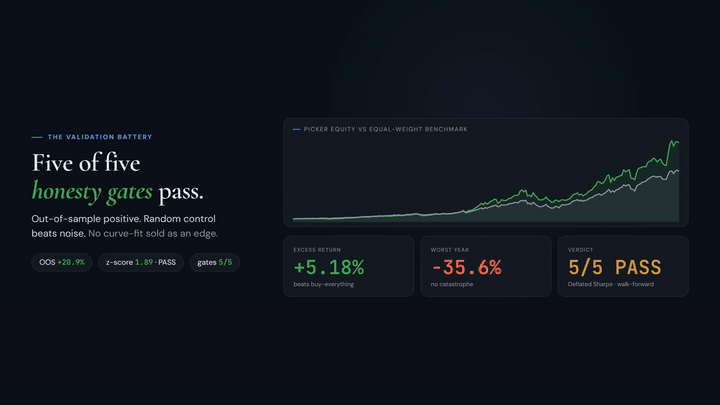
A plain-language ask flows through to a ranked, validated, deployable result — real market data, no API keys.
The real report
Self-contained HTML deliverables, generated on free daily market data. English-primary, dark institutional look.
What you actually see — Stock Picker
Rank your universe, validated against buying everything.
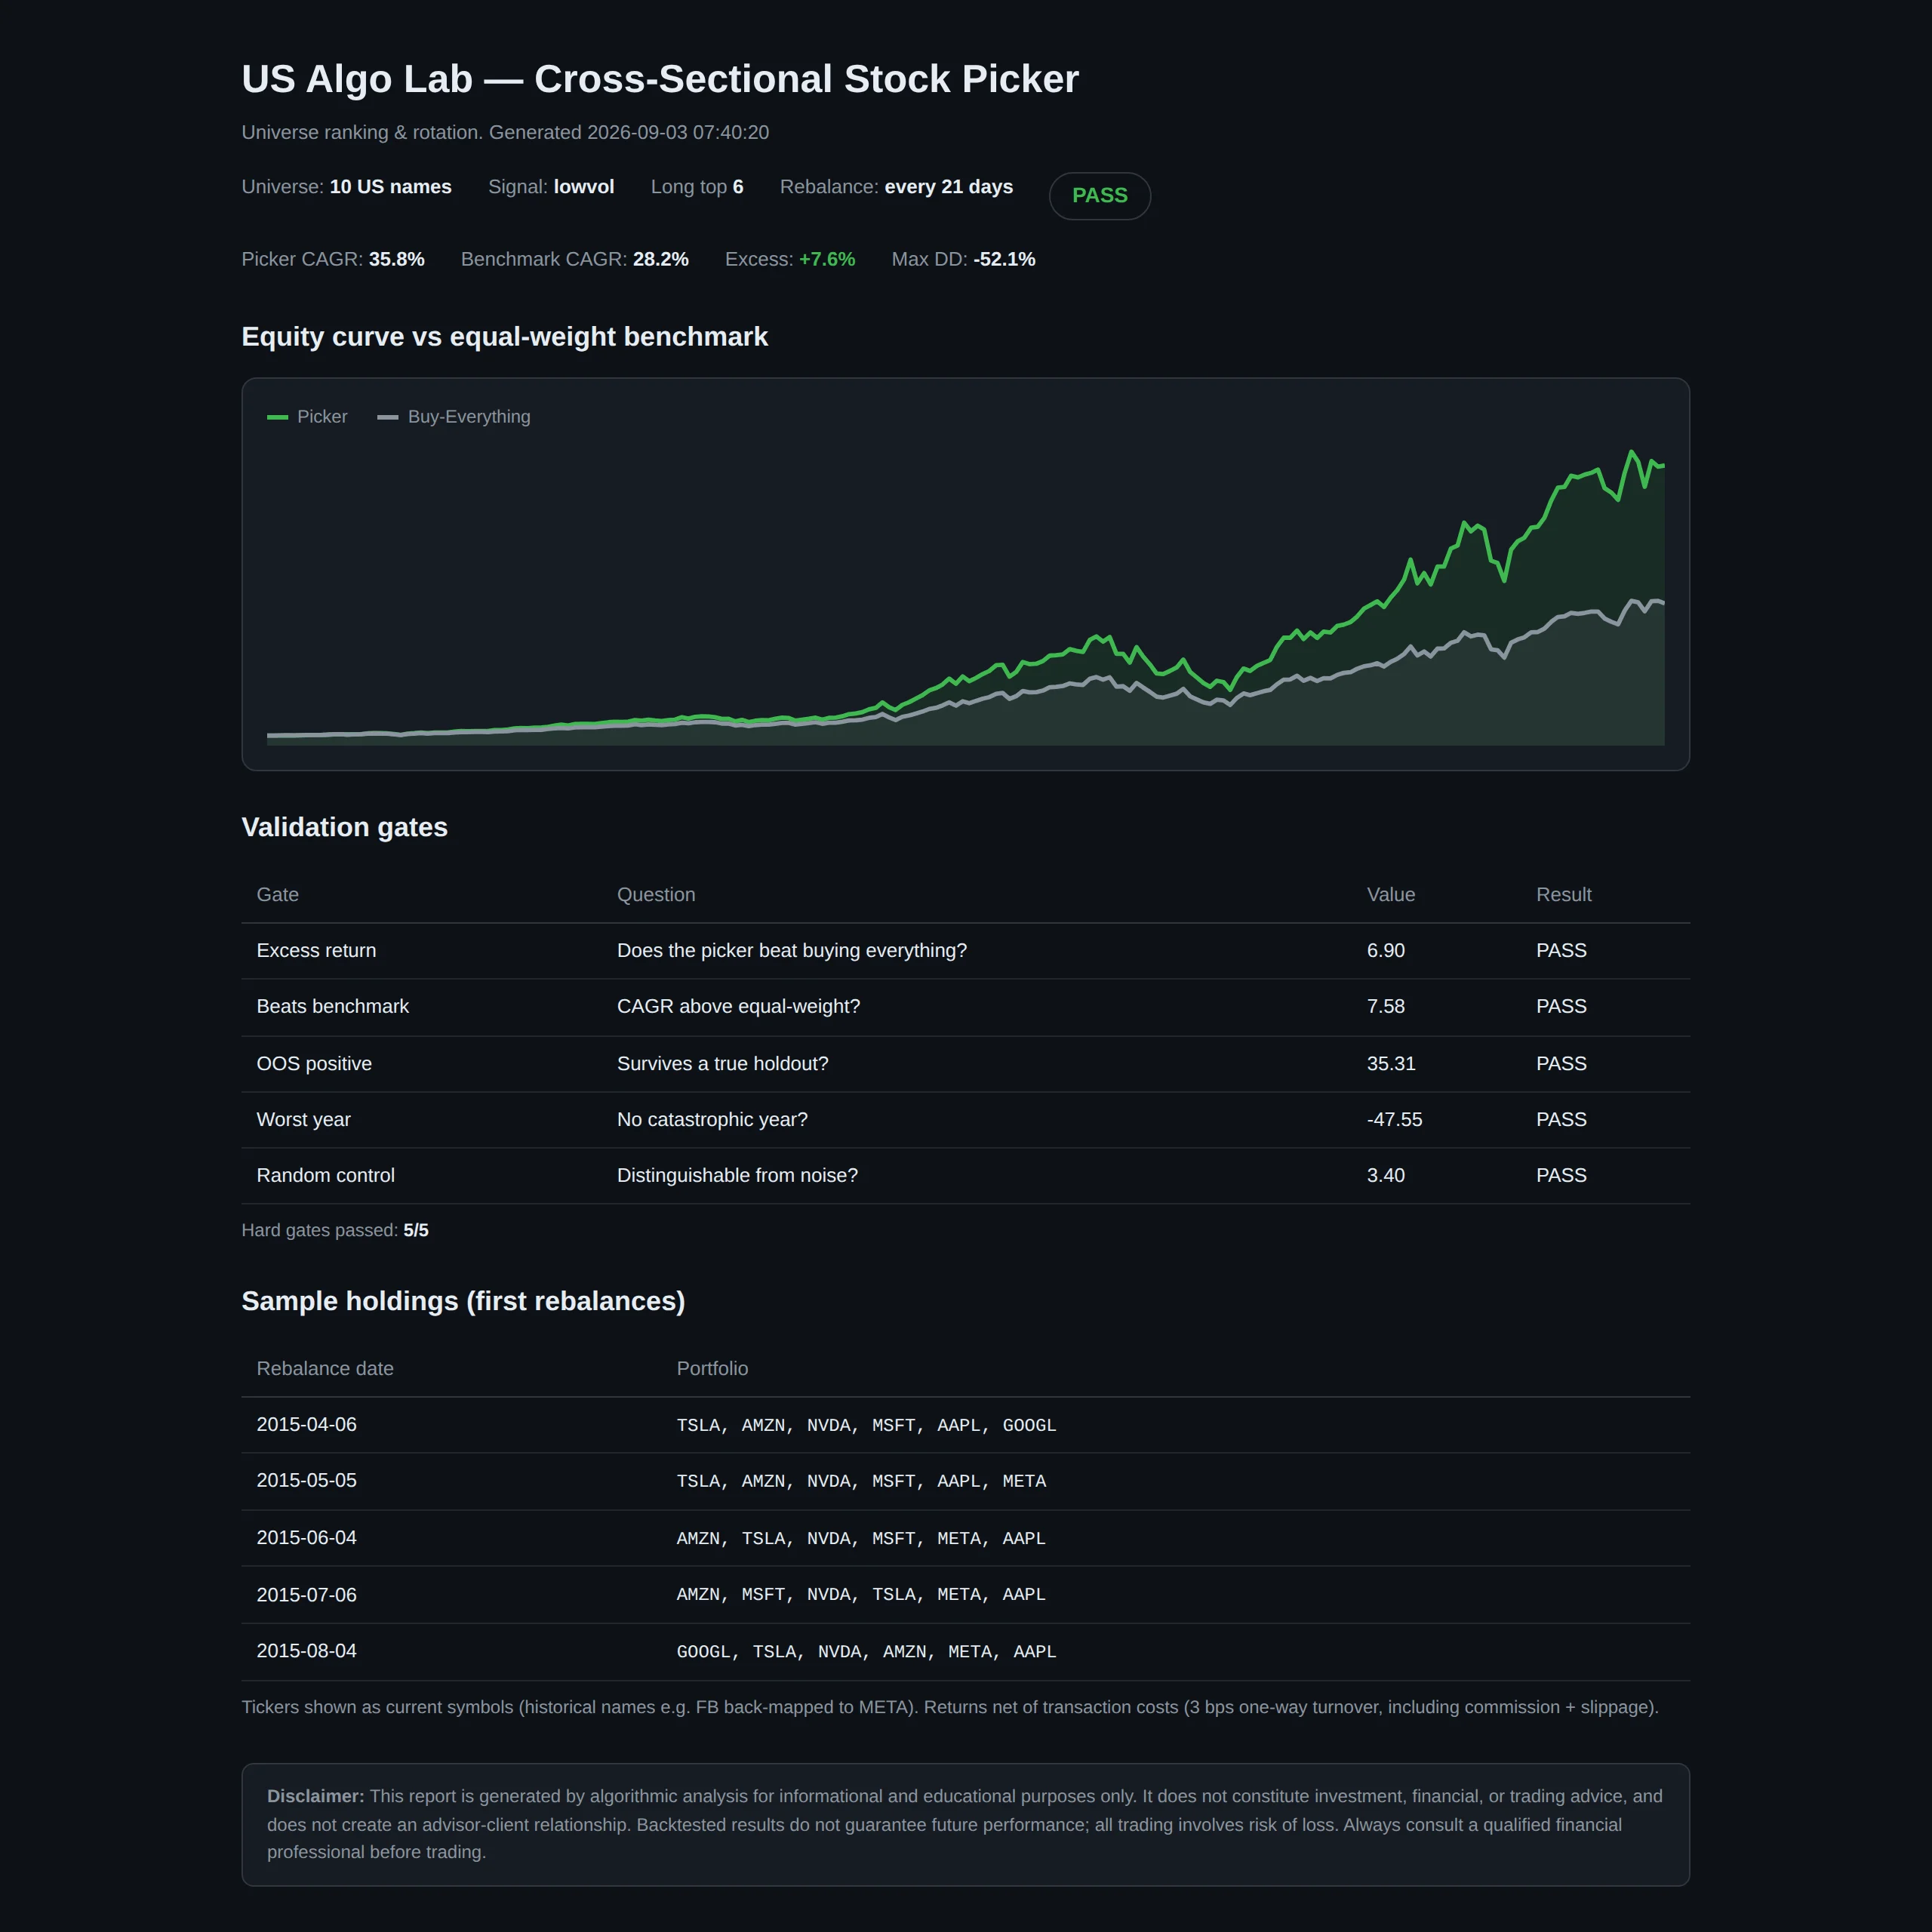
The verdict — 5/5 hard gates PASS for the verified low-volatility screen, shown honestly.
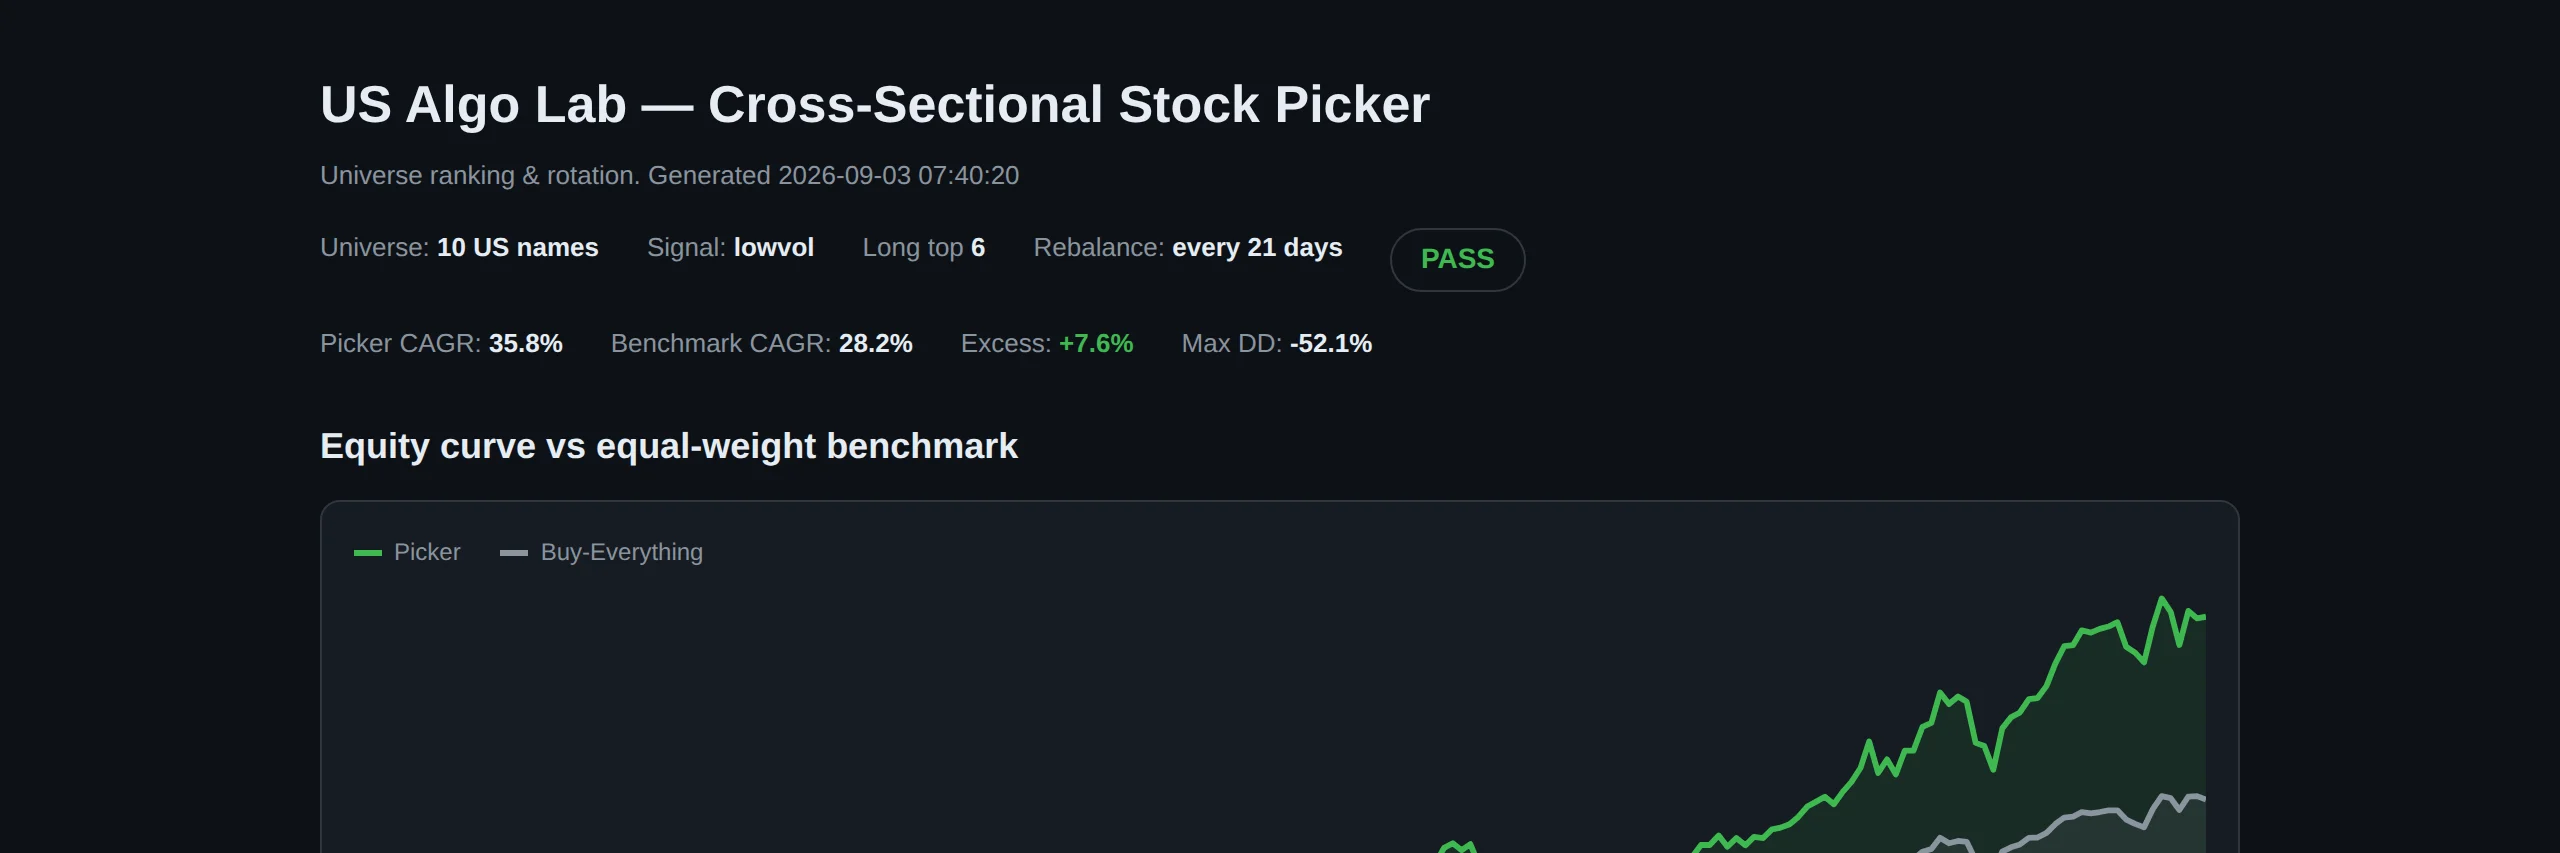
- Picker CAGR 35.8% vs 28.2% equal-weight benchmark — excess +7.6 pp
- 5/5 validation gates PASS for the verified 63-day low-volatility screen, including random-control permutation (z = 3.40)
- Per-rebalance holdings table with transaction-cost and ticker-back-mapping disclosures
What you actually see — Strategy Discovery
Sweep 8 classic families over 56 configs — and get the truth about whether any survive.
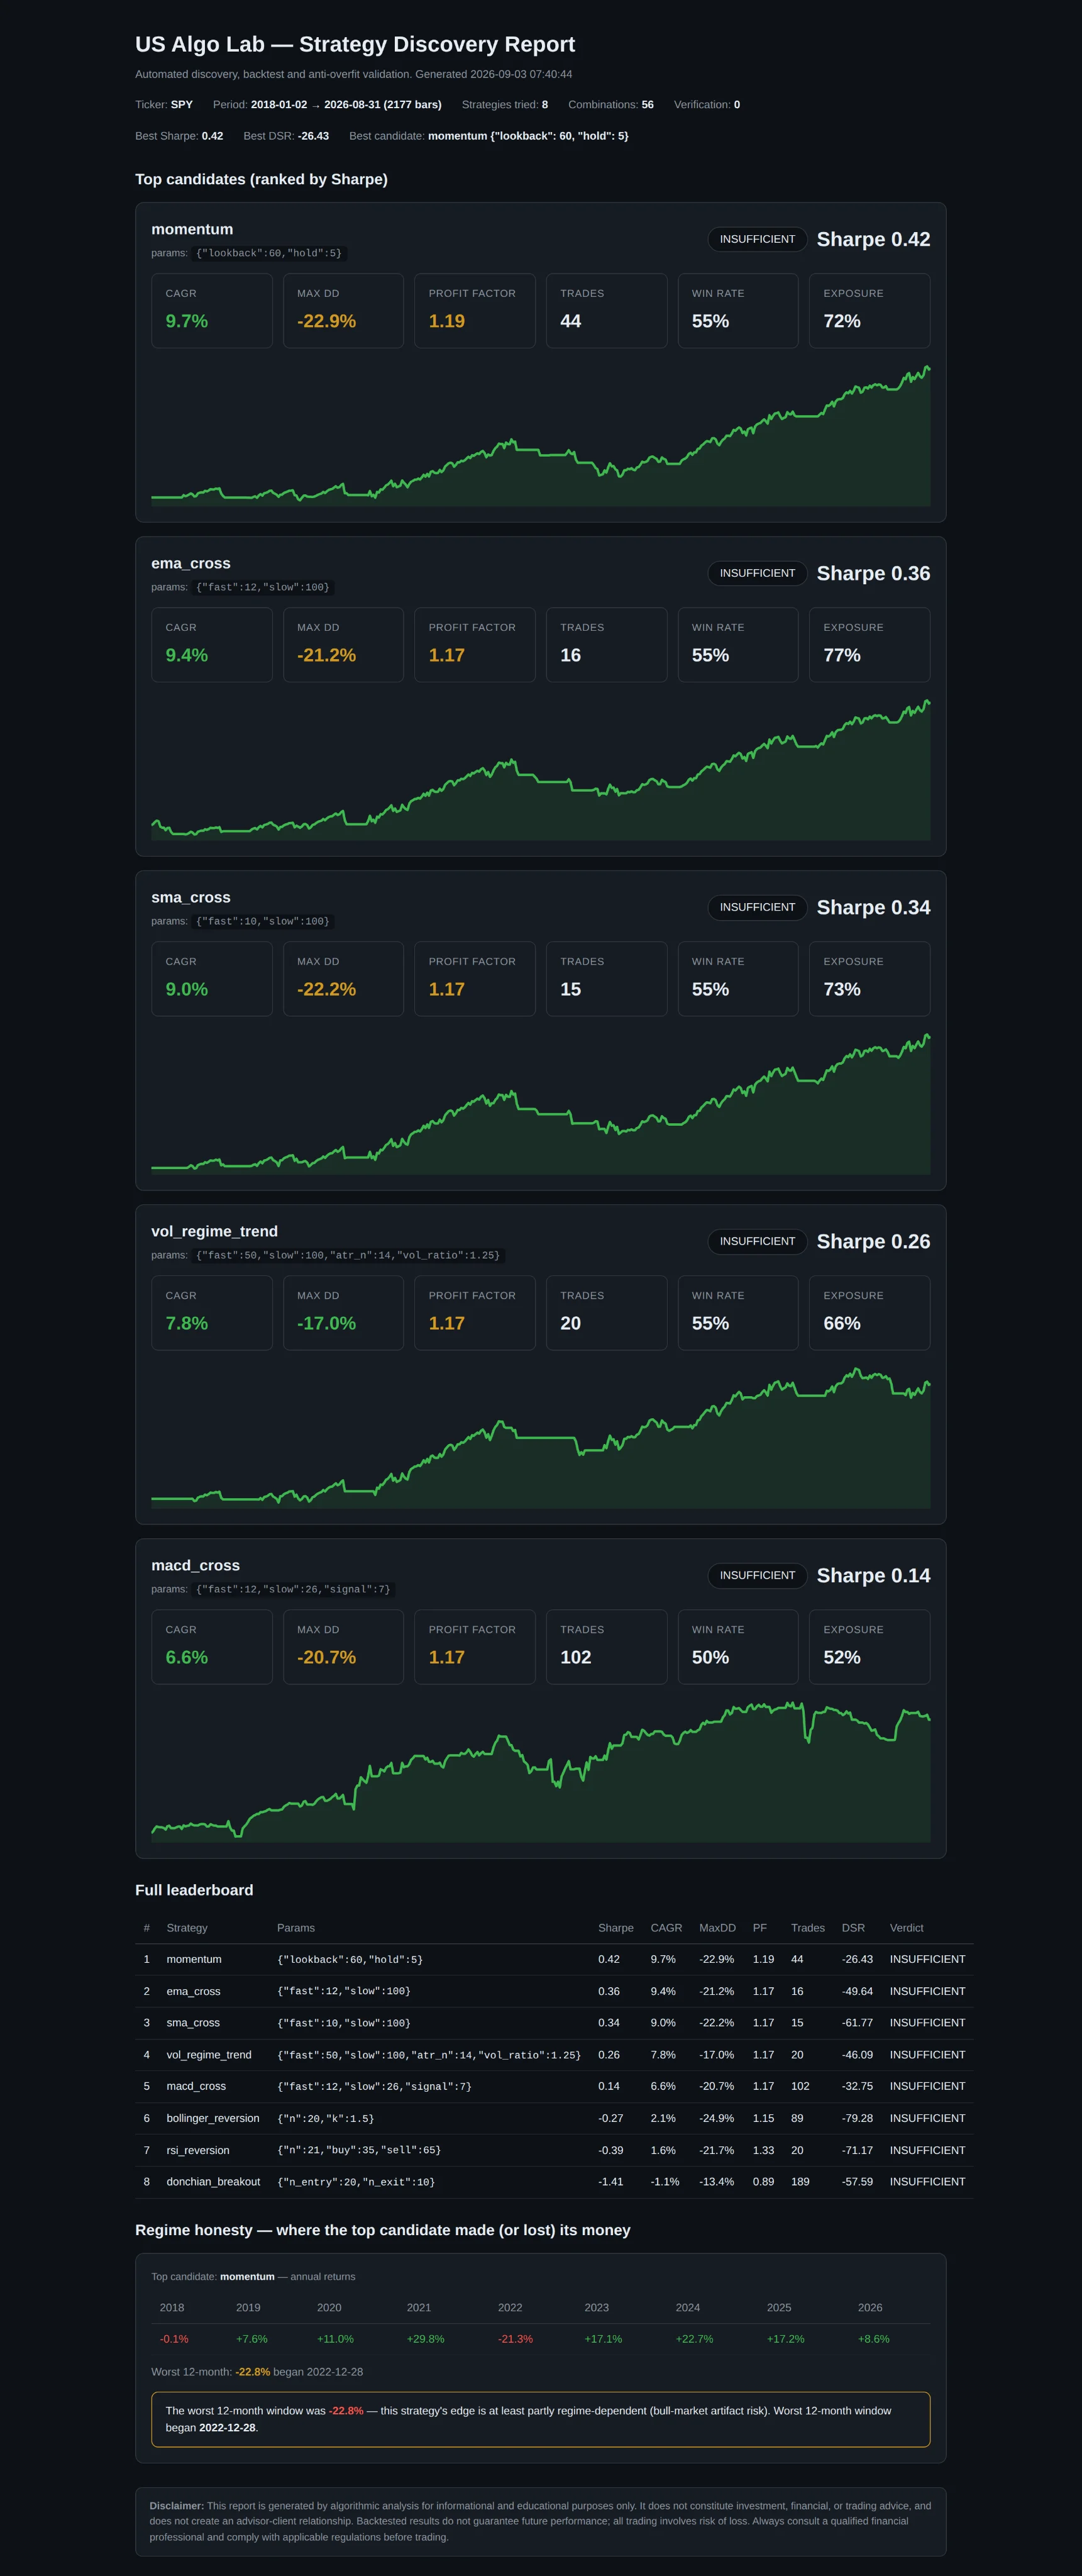
When the edge is noise, it says so plainly.
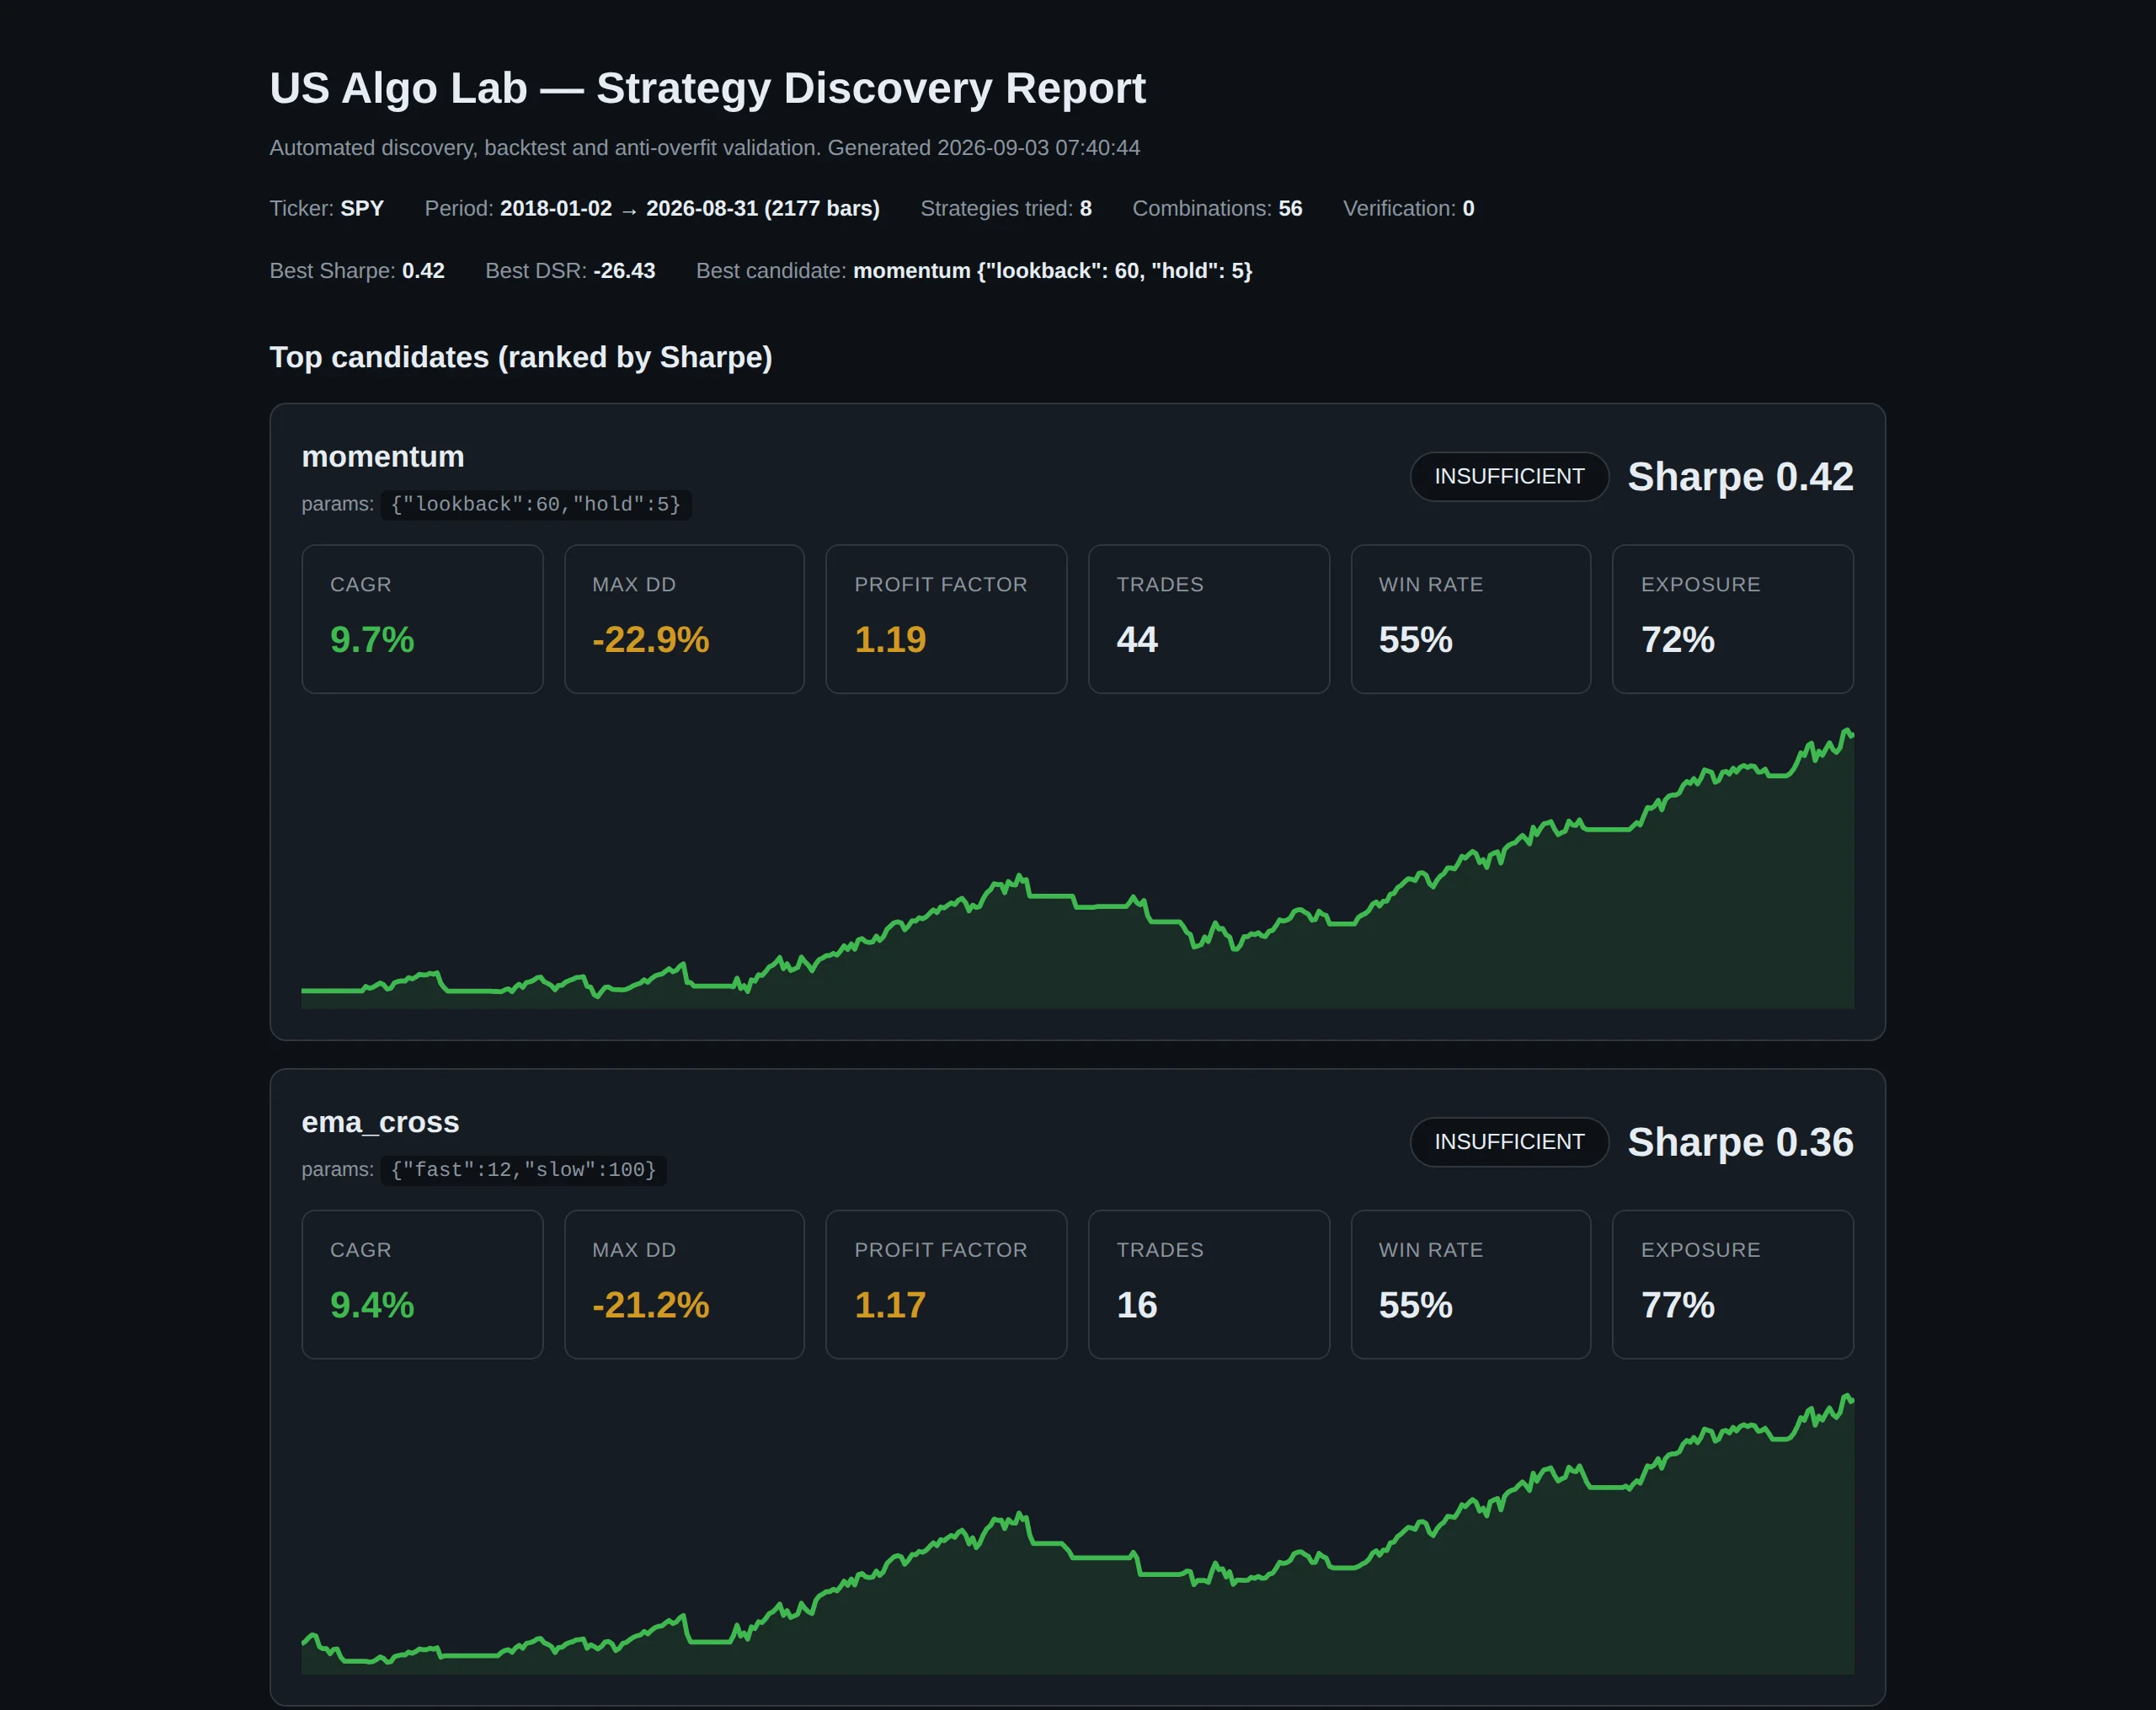
- Full leaderboard of all 8 families ranked by Sharpe
- Deflated Sharpe corrects for how many configs you tried
- When nothing survives, it says NOISE — never sells you a curve-fit
What you get
1. Stock picking (headline) — ranks any US universe by momentum (12/6/3-month, 12-1), low volatility, or mean reversion. Holds the top N equal-weight, rotates on a schedule, validated against a buy-everything benchmark.
2. Strategy discovery — sweeps 8 classic families (SMA/EMA/MACD cross, RSI/Bollinger reversion, Donchian breakout, momentum, vol-regime trend) over parameter grids to find what works for your tickers.
3. Anti-overfit validation — every candidate runs through Deflated Sharpe, walk-forward, out-of-sample split, and a random-control permutation test. Most real scans surface noise — this tool says so plainly instead of selling you a curve-fit.
4. IBKR paper deployment — generates a ready-to-run ib_insync script for your IBKR Paper account. You review it, you run it locally. No live orders from the cloud, no hosted credentials.
The validation gates
| Gate | Threshold |
|---|---|
| Excess return | > 0 |
| Beats benchmark | CAGR > equal-weight |
| OOS positive | OOS CAGR > 0 |
| Worst year | > -50% |
| Random control | z > 1.5 |
PASS requires all hard gates. Any failure is surfaced as INSUFFICIENT — never masked, never spun.
The honest edge
Most "strategy finder" tools hand you the flashiest equity curve. This one tells you the likelihood it's overfit. That honesty is the product — and it's what survives real markets.
Deployment boundary
The skill generates a reviewable ib_insync script for IBKR Paper (port 7497). You run it locally on your own machine. The cloud never executes live orders and never holds your broker credentials.
Example requests
- "Which of my watchlist should I hold next month?"
- "Is this moving-average crossover real edge or overfit noise?"
- "Pick the top 5 of these ETFs by low volatility."
- "Generate an IBKR paper-trading script for the best momentum config."
Who it's for
- Retail traders building a disciplined, rules-based approach to US equities
- Watchlist managers who want evidence before adding names
- Quant-curious investors who want institutional validation without the quant degree
- Anyone burned by backtests that "look great" but die on paper
Requirements
- Python 3.9+, pandas, numpy on the machine where you run the generated deployment script
- scipy optional (pure-stdlib fallback included)
- The discovery/picking itself runs entirely on Capafy with free public data
For informational and educational purposes only. Not financial, investment, or trading advice. Backtested results do not guarantee future performance; all trading involves risk of loss. Consult a qualified financial professional before trading.